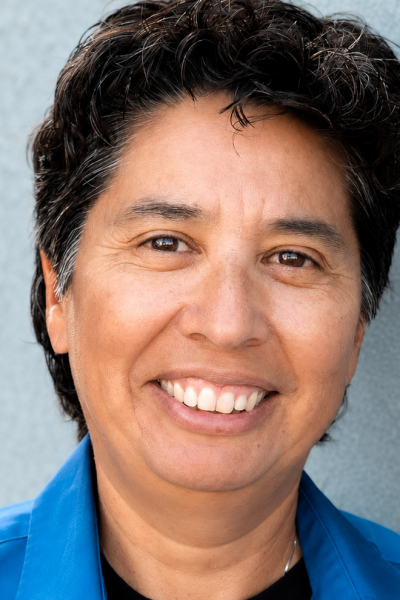
Julie Crittenden
Mortgage Broker | CDLP, CRMP, CLA
NMLS #1816130 | DRE #01801629
(619) 992-6044
For more than twenty years, I owned an environmental inspection company that brought me into other people's homes every day. Each one held a lifetime of memories. For most families, it was also their greatest asset.
My parents showed me its quieter power. The equity they built over the decades gave them options. Those options became freedom, peace of mind, and years of adventure in retirement.
Every conversation starts with the years ahead, not the loan. Your family is always welcome at the table.
Together, we shape a plan both spouses can carry forward with confidence.
Explore divorce mortgage planning →
Every loan type, measured against your long-term plan, not just today's rate.
A second set of eyes when housing is part of your client's plan.
Explore advisor partnerships →
When I'm not working, you'll find me serving on my HOA board, at the dog park, or walking my dog, Echo.
Homeowners 62 and older with sufficient equity in their primary residence may qualify for a government-insured reverse mortgage, known as a HECM, and some programs begin at age 55. Borrowers continue paying property taxes, insurance, and home maintenance. Julie Crittenden reviews eligibility, costs, and options with homeowners and their families in plain language.
It depends on how the settlement is structured and what the existing loan allows. Some homeowners refinance the loan into their own name. Others keep the existing loan in place, or assume it, when the loan type and lender allow. Each path carries its own title, tax, and liability considerations. Reviewing them while the settlement is still being negotiated keeps more of these options open.
An equity buyout can be structured several ways. The spouse keeping the home may refinance and use the proceeds to pay the other spouse, assume the existing loan where the lender allows, or offset the equity with other assets in the settlement. Title, taxes, and the loan options available all shape which structure works, so they are worth reviewing before the terms are set.
It depends on how the support is written and received. Alimony and child support can count as qualifying income when the payments are documented and expected to continue for a required period. Each loan program has its own rules for both. Reviewing the wording while the settlement is still being negotiated keeps that option open.
Julie Crittenden offers all major loan types, including reverse mortgages, conventional, FHA, VA, jumbo, cash-out refinance, home equity lines of credit, and investor loans.
Borrow smart, repay smart means every loan makes sense from the day it closes to the day it is repaid. Before any decision is made, Julie explains the cost, the terms, and how the loan fits your long-term plan.
Julie Crittenden is licensed in California, Arizona, Colorado, Florida, Mississippi, Oklahoma, Tennessee, Washington, and Wisconsin, with an office in San Diego.
A consultation is a 30-minute conversation about your goals and your situation. Julie explains your options clearly and answers your questions, with no pressure and no obligation.